
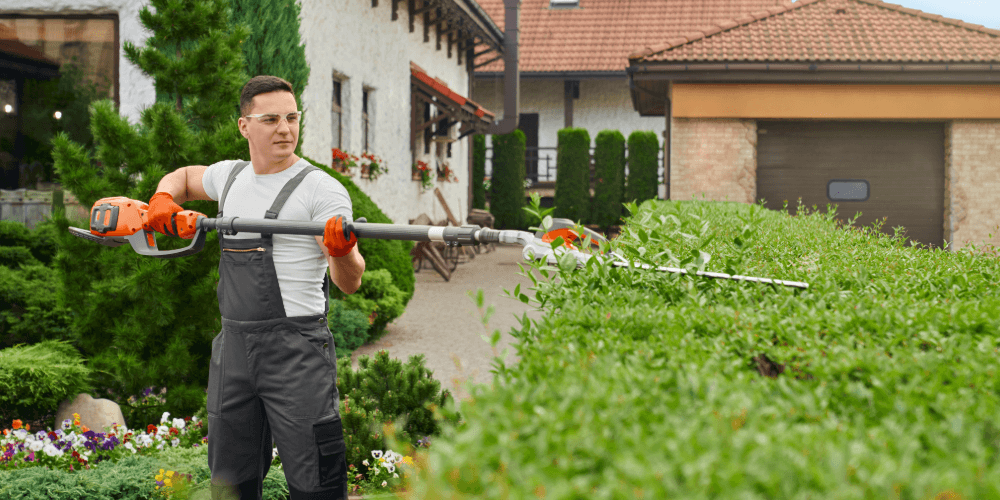


Gardeners & Landscapers
How to Choose the Right Van Insurance: Gardeners and Landscapers
 17 November 2026
 7 min read
If you work as a gardener or landscaper, your van is more than just a way to get from A to B. It carries the tools, machinery and materials you need to complete your jobs. Without it, keeping your business running could become difficult.
Choosing the right van insurance is therefore an important part of protecting your business. However, not every policy offers the same level of cover. You need to consider how you use your van, what you carry and who drives it.
In this guide, we explain how to choose the right van insurance for gardeners and landscapers, including the key features to look for when comparing policies.
1. Choose the Right Type of Van Insurance
The first step is to make sure your policy covers how you actually use your van.
If you use your vehicle to travel between customers, transport gardening equipment or carry landscaping materials, you will usually need business van insurance rather than standard social-use cover.
You may also need carriage of own goods insurance. This type of cover is designed for businesses that transport their own tools, equipment, materials or stock.
For example, a gardener carrying lawnmowers and hedge trimmers to different properties may need this type of business use.
If you transport goods belonging to other people in return for payment, you may need hire and reward insurance instead. Always explain your activities to your insurer so they can identify the correct cover.
2. Compare the Different Levels of Cover
Once you understand the type of insurance you need, consider how much protection you want.
Most van insurance policies offer three main levels of cover:
Third Party Only: Covers injury or damage you cause to other people and their property. It does not cover damage to your own van.
Third Party, Fire and Theft: Includes third-party cover, plus protection if your van suffers fire damage or theft.
Comprehensive: Can cover damage to your own van, as well as third-party claims, fire and theft, subject to the policy terms.
For gardeners and landscapers who rely on their vans every day, comprehensive van insurance may be worth considering. Repairing or replacing a work vehicle could be expensive, particularly if an accident stops you from completing jobs.
However, the most expensive policy is not automatically the best. Compare the benefits, exclusions and excess before making a decision.
3. Check Whether Your Tools and Equipment Are Covered
Gardeners and landscapers often carry expensive equipment in their vans. This might include:
Lawn mowers and strimmers.
Hedge trimmers and chainsaws.
Leaf blowers.
Spades, forks and other hand tools.
Landscaping machinery and equipment.
Do not assume your van insurance automatically covers everything inside it.
You may need separate tools and equipment insurance to protect these items against theft, accidental damage or loss.
Check whether your policy covers tools:
While travelling between jobs.
When stored inside your van overnight.
While working at a customer's property.
When you leave equipment at a job site.
Some insurers apply security requirements, such as locking tools inside a secure vehicle or storing them in an approved location overnight.
4. Consider Who Needs to Drive Your Van
If you work alone, a policy covering you as the main driver may be enough.
However, if you employ staff, work with subcontractors or share vehicles with other gardeners, you may need additional driver cover.
Some insurers offer named driver policies, while others provide any driver van insurance. The latter can offer greater flexibility when several people need access to your vehicles.
Before choosing a policy, check:
The minimum age for additional drivers.
Whether drivers need a minimum number of years' experience.
Whether previous claims or convictions affect eligibility.
Whether staff and subcontractors can drive the vehicle.
Make sure every driver meets the policy requirements before they get behind the wheel.
5. Look at Breakdown and Replacement Vehicle Cover
What would happen if your van broke down or suffered damage in an accident?
For many gardeners and landscapers, losing access to a vehicle can mean cancelled appointments, delayed projects and lost income.
Breakdown cover can help if your van becomes undriveable while travelling. Depending on the policy, it may include roadside assistance, recovery or onward travel.
You could also consider a replacement vehicle or courtesy van benefit. This may help you continue working while your own van undergoes repairs.
Check whether the replacement vehicle is suitable for your business. A small car might not help much if you need to transport lawnmowers, machinery and landscaping materials.
6. Compare the Cost of Van Insurance
Van insurance premiums vary depending on your circumstances and the level of cover you choose.
Insurers may consider:
Your age and driving history.
Your van's make, model and value.
Your annual mileage.
Your occupation and business activities.
Where you park your van overnight.
The number of drivers on your policy.
Your previous claims history.
You can help insurers provide an accurate quote by giving them honest information about your business.
It is also worth reviewing your policy if your business grows, you buy new equipment or you start offering additional services.
Find the Right Van Insurance for Your Gardening Business
Your van plays an important role in keeping your gardening or landscaping business moving. Choosing suitable insurance can help protect your vehicle and support your business if something goes wrong.
At Insurance Revolution, we understand that every gardening and landscaping business has different requirements. Our team can help you explore van insurance options that reflect your vehicle, working arrangements and business needs.
Whether you are a self-employed gardener or run a team of landscapers, we can help you find suitable cover.
Get a van insurance quote for gardeners or landscapers today or speak to our team on 0330 808 1404.
Frequently Asked Questions
Do gardeners need business van insurance?
If you use your van for work, such as travelling between customers or carrying gardening equipment, you will usually need business van insurance. Your insurer must know how you use your vehicle.
Does van insurance cover gardening tools?
Not automatically. You may need separate tools and equipment insurance to protect items stored in your van or taken to job sites. Always check your policy conditions.
Can I insure multiple vans for my landscaping business?
Yes. If you operate several vehicles, fleet van insurance may allow you to cover them under one policy. This can make managing your business vehicles easier.
Is comprehensive van insurance worth it for gardeners?
It may be worthwhile if you rely on your van to earn a living. Comprehensive cover can protect your own vehicle against accidental damage, subject to the policy terms, as well as providing third-party protection.
Sources


Related Articles
When Should Plumbers Consider Fleet Insurance?
As your plumbing business grows, you may find yourself investing in additional vans, taking on employees and managing more jobs across different locations. While this growth can create new opportunities, it also brings extra responsibilities. One of these is making sure your business vehicles have the right insurance.

How to Choose the Right Van Insurance: Plumbers
If you're a plumber, your van is one of the most important tools in your business. You rely on it to travel between jobs, carry plumbing equipment and transport materials to customer properties.
When Should You Consider Fleet Insurance? Gardeners and Landscapers
As your gardening or landscaping business grows, you may find yourself investing in more vans, hiring staff and taking on larger contracts. While this creates new opportunities, it also brings extra responsibilities, including managing your business vehicles.