



Business Interruption Insurance UK: What It Covers & Why It Matters for SMEs
Unexpected disruptions can be damaging for any organisation, but for small and medium-sized enterprises (SMEs), even a short-term interruption may…

Cover for lost income and ongoing costs if a fire, flood or other insured event stops you trading, so a single incident doesn’t close your business for good.
Cover for lost income and ongoing costs if a fire, flood or other insured event stops you trading, so a single incident doesn’t close your business for good.
 Lost gross profitFixed costs & wagesTemporary premises
 Compare from 20+ Trusted Insurers

Speak to a specialist 0330 027 0996
Business interruption insurance replaces lost income and covers ongoing costs, such as rent and salaries, if an insured event like fire or flood stops you trading. It’s designed to put you back in the financial position you’d have been in if the event hadn’t happened.
Business interruption can be written on a loss of gross profit basis or a loss of gross income basis, depending on how your business earns. We will tell you which fits yours.
It usually only pays out alongside a valid claim on your buildings or contents insurance, it’s rarely sold as a standalone policy.
Business interruption insurance can include:
 Loss of gross profit or gross incomeRent and fixed costsStaff wagesCover for a set indemnity periodLoss of a key customer or supplierDenial of access to your premises
Public Liability
Covers claims if your business injures a customer or damages their property.
Employers’ Liability
A legal requirement once you employ staff, covering workplace injury claims.
Professional Indemnity
Covers claims that your advice or design was negligent and caused a loss.
Business Contents
Protects equipment, stock and fixtures against fire, theft and damage.
Cyber Insurance
Covers the cost of a cyber attack or data breach, including lost trading time.
What triggers a business interruption claim?
What triggers a business interruption claim?
Business interruption almost always rides alongside a claim on your buildings or contents policy, not on its own.
Business interruption almost always rides alongside a claim on your buildings or contents policy, not on its own.
| Insured event | What has to happen | What BI then covers |
|---|---|---|
Fire | A valid claim on your buildings or contents insurance | Lost gross profit or gross income while you can’t trade or operate normally |
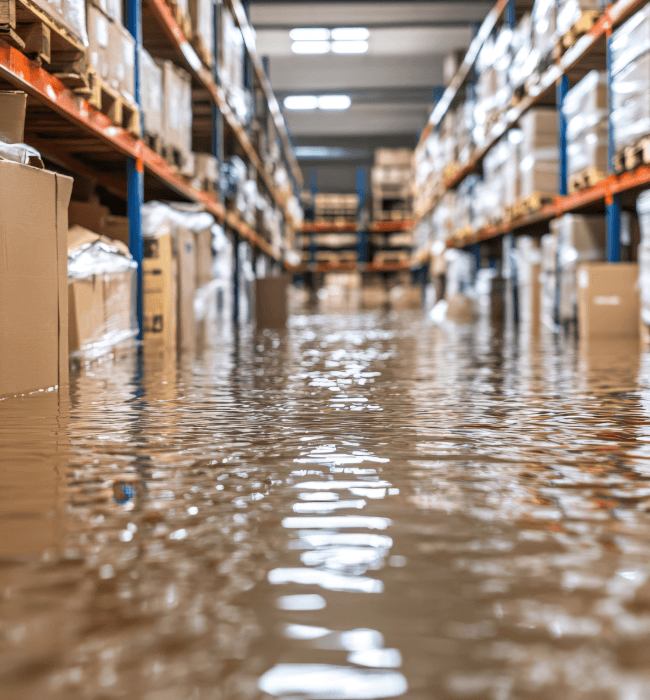
Flood or escape of water | Water damage significant enough to stop normal trading | Rent, wages and increased costs while repairs are carried out |
Theft or malicious damage | A break-in or vandalism that damages stock or premises | Lost income and the cost of replacing stolen or damaged stock |
Denial of access | An event nearby, like a gas leak, that closes your street | Lost trading time even though your own premises are undamaged |

Top Tip
Most standard policies don’t cover pandemics, a notifiable disease, or losing a key customer or supplier, unless you’ve specifically extended your cover to include them, check your policy wording rather than assuming.
What could a closure actually cost you?
What could a closure actually cost you?
A short closure can cost far more than the repair bill itself, once lost trading and ongoing overheads are added up.
A short closure can cost far more than the repair bill itself, once lost trading and ongoing overheads are added up.

Short closure
A small fire closes a shop for repairs and redecoration.
Typical cost
£5,000-£30,000

Flood damage
A burst pipe floods a restaurant kitchen for several weeks.
Typical cost
£20,000-£100,000
Major fire
A serious fire destroys stock, equipment and premises.
Typical cost
£100,000-£500,000+
Temporary premises
You trade from an alternative site while repairs continue.
Typical cost
Ongoing rent and wages
There’s no fixed price for business interruption insurance. Your premium depends mainly on your gross profit or gross income, the indemnity period you choose, your premises and your claims history.

Gross profit or income
Your sum insured is based on gross profit or gross income, so higher-turnover businesses pay more to insure.

Level of cover
Adding increased cost of working or denial of access extends your protection and your premium.
Indemnity period
A 24-month period costs more than 12 months, but gives you longer to fully recover.
Business type
Businesses that can trade from an alternative site recover faster and often pay less.

Type of premises
A commercial kitchen carries more fire risk than an office, and is priced accordingly.
Claims history
A clean claims record helps keep premiums down at renewal.
How to get business interruption insurance
How to get business interruption insurance
Simple steps. Expert advice on the cover and indemnity period that fit your business.
Simple steps. Expert advice on the cover and indemnity period that fit your business.

Tell us about your business
Your turnover, gross profit and premises.

Choose your indemnity period
12, 24 or 36 months, based on how long recovery could take.

We compare specialist insurers
We search our panel of 20+ UK insurers.

Get covered and protected
Receive your documents, usually the same day.
 UK-based specialist advisersAccess to specialist insurersNo obligation, just expert help
Trusted by thousands of businesses across the UK
Trusted by thousands of businesses across the UK
From everyday business insurance to complex specialist cover, our customers trust Insurance Revolution to find the right protection and provide expert support when it matters.
From everyday business insurance to complex specialist cover, our customers trust Insurance Revolution to find the right protection and provide expert support when it matters.
Business interruption guides
Business interruption guides
Practical advice on cover, indemnity periods and claims.
Practical advice on cover, indemnity periods and claims.
Business Interruption Insurance UK: What It Covers & Why It Matters for SMEs
Unexpected disruptions can be damaging for any organisation, but for small and medium-sized enterprises (SMEs), even a short-term interruption may…
Business Interruption Insurance vs Income Protection: What’s the Difference?
When business operations are halted or income suddenly stops, having the right protection in place can make a significant difference. However,…
Top 5 Claims Paid by Business Interruption Insurance (And What Wasn’t Covered)
Business interruption insurance is designed to support businesses when operations are disrupted due to unexpected events. From fire damage to supply…
What Isn’t Covered by Business Interruption Insurance?
Business interruption insurance can help your business recover after an unexpected event. It can replace lost income and help cover ongoing costs…
Business interruption insurance FAQs
Business interruption insurance FAQs
Straight answers on cover, indemnity periods, gross profit and claims.
Straight answers on cover, indemnity periods, gross profit and claims.
Business interruption insurance replaces lost income and covers ongoing costs, such as rent and wages, if an insured event like fire or flood stops you trading. It puts you back in the financial position you’d have been in without the event.
Still have questions?
Our advisers are here to help you find the right solution.