



Builder Insurance Claims Guide: What to Do When Tools Are Stolen or Accidents Happen
Builders face a variety of risks on-site, including theft of valuable tools and unexpected accidents that can disrupt projects and impact earnings.…

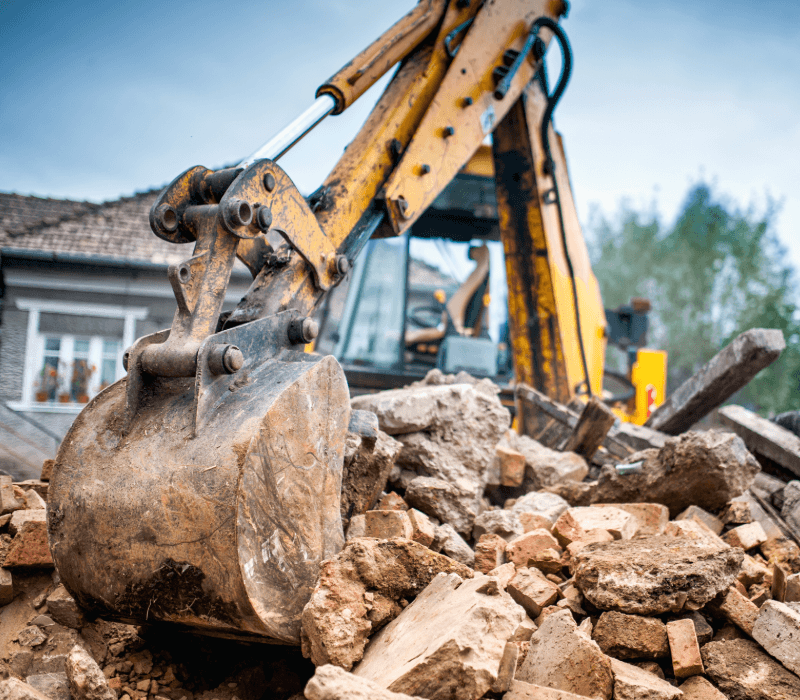
Public liability and plant cover built for demolition contractors, including the higher limits this trade typically needs given the risk to adjacent structures.
Public liability and plant cover built for demolition contractors, including the higher limits this trade typically needs given the risk to adjacent structures.
 Neighbouring propertyPlant & machineryDebris removal
 Compare from 20+ Trusted Insurers

Speak to a specialist 0330 027 0996
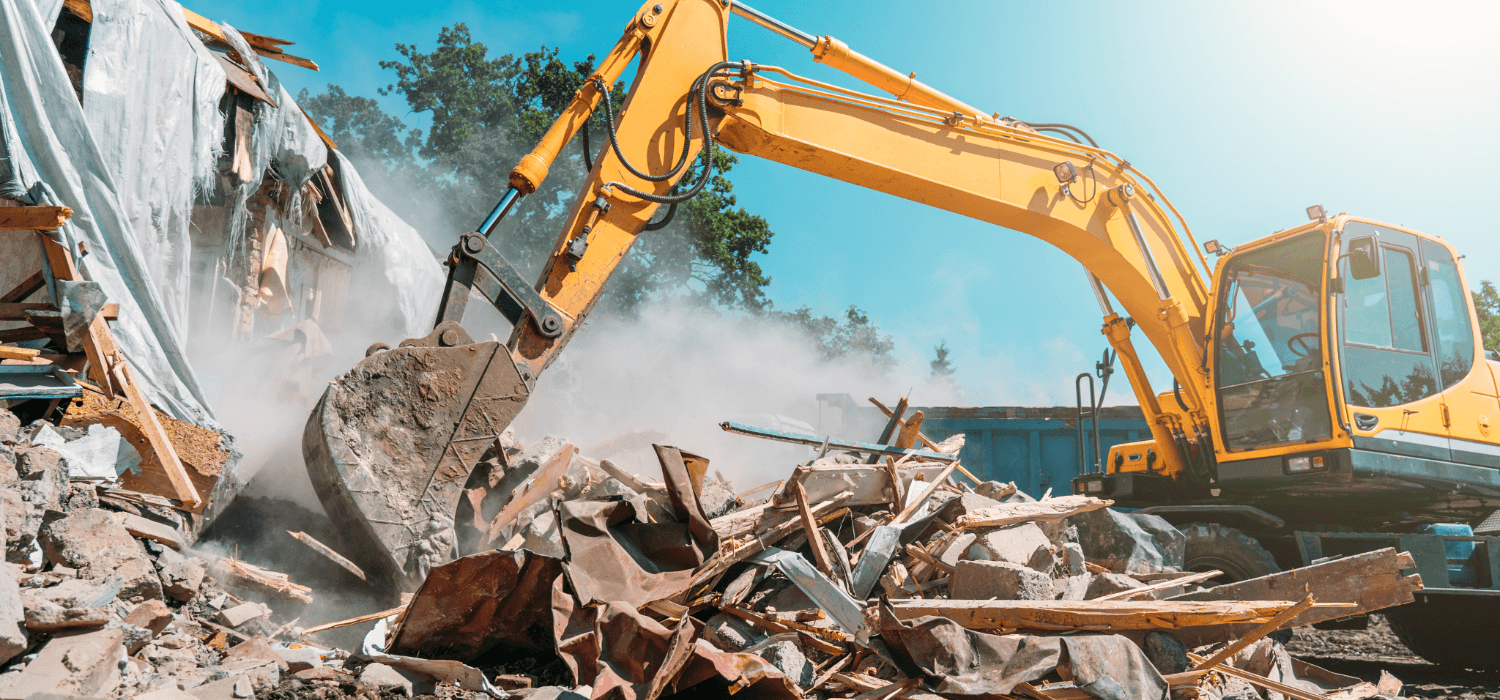
Demolition insurance is a combination of covers built around taking down structures safely, public liability for injury or damage, employers’ liability if you have staff, and plant cover for the machinery you use. Because demolition can affect neighbouring buildings, underground services and public areas, this trade typically carries higher liability limits than most.
Older buildings can involve asbestos or other hazardous materials, which need their own licensed procedures separate from your general liability cover, check what your policy requires before taking on this kind of work.
Demolition insurance can include:
 Public liabilityEmployers’ liabilityPlant & machineryProfessional indemnity (if you design)Underground services damageBusiness van & HGV insurance (separate)
Public Liability
Covers claims if your business injures a customer or damages their property.
Employers’ Liability
A legal requirement once you employ any staff, even casual help.
Professional Indemnity
Covers claims that your demolition method or sequencing was negligent.
Plant & Machinery
Covers excavators, breakers and other plant you own or hire.
Tools & Equipment
Covers your smaller tools against theft from the van or site.
How much public liability cover does demolition need?
How much public liability cover does demolition need?
This is one of the highest-risk trades on a site, many demolition contractors carry limits well above the £1-2 million common elsewhere.
This is one of the highest-risk trades on a site, many demolition contractors carry limits well above the £1-2 million common elsewhere.
| Level of cover | Typical for | Watch out for |
|---|---|---|
£2 million | Small-scale internal strip-outs | May be too low for most demolition contracts |
£5 million | General demolition contracts | A common minimum for principal contractors |
£10 million | Larger structures or work near neighbouring buildings | What many commercial contracts require |
Beyond £10 million | Major contracts or specified requirements | Usually only needed if the contract specifies it |

Top Tip
Check what your main contractor or local authority requires before choosing a limit, demolition often has a higher minimum than any other trade on the site.
There’s no fixed price. It depends on the scale of demolition you do, whether you own or hire plant, whether you have staff and your claims history.
Scale of demolition
Full structural demolition carries more risk than internal strip-outs.
Number of staff
More employees increase your employers’ liability exposure.
Proximity to other buildings
Work near neighbouring structures increases the risk insurers price in.

Level of cover
Higher public liability limits, common in this trade, increase your premium.
Plant ownership
Owning plant adds machinery risk on top of your liability cover.
Claims history
A clean claims record helps keep premiums down at renewal.
How to get demolition insurance
How to get demolition insurance
Getting demolition insurance takes four steps: tell us about your work, choose your cover level, compare specialist insurers, then get covered, often the same day.
Getting demolition insurance takes four steps: tell us about your work, choose your cover level, compare specialist insurers, then get covered, often the same day.

Tell us about your work
The scale of demolition you do, and whether you have staff or plant.

Choose your cover level
£2 million up to £10 million or more, based on your contracts.

We compare specialist insurers
We search our panel of 20+ UK insurers.

Get covered and working
Receive your documents, usually the same day.
 UK-based specialist advisersAccess to specialist insurersNo obligation, just expert help
Trusted by thousands of businesses across the UK
Trusted by thousands of businesses across the UK
From everyday business insurance to complex specialist cover, our customers trust Insurance Revolution to find the right protection and provide expert support when it matters.
From everyday business insurance to complex specialist cover, our customers trust Insurance Revolution to find the right protection and provide expert support when it matters.
Demolition insurance guides
Demolition insurance guides
Practical advice on cover levels, plant and staying protected.
Practical advice on cover levels, plant and staying protected.
Builder Insurance Claims Guide: What to Do When Tools Are Stolen or Accidents Happen
Builders face a variety of risks on-site, including theft of valuable tools and unexpected accidents that can disrupt projects and impact earnings.…
Contract Works Insurance Explained: Why Every Builder Should Have It
Building projects can involve multiple risks, from damage to works in progress to unexpected delays. For builders, contractors, and tradespeople,…
Contract Works & Plant Cover for Builders: What You Need to Know
Building projects often come with a wide range of risks, particularly when valuable materials, tools, and machinery are involved. Whether working on…
Demolition insurance FAQs
Demolition insurance FAQs
Straight answers on cover levels, plant, neighbouring properties and cost.
Straight answers on cover levels, plant, neighbouring properties and cost.
Demolition insurance is a combination of covers built around taking down structures safely: public liability for injury or damage, employers’ liability if you have staff, and plant cover for machinery you own or hire.
Still have questions?
Our advisers are here to help you find the right solution.
Related trades we cover
Related trades we cover
Demolition contractors often work alongside these trades. Each has its own cover requirements.
Demolition contractors often work alongside these trades. Each has its own cover requirements.
Groundworks Insurance
Excavation and foundations once the site has been cleared.
Scaffolder Insurance
Temporary structures and access, often needed before demolition starts.
Builders Insurance
Main contractors managing demolition within a wider project.