

Small BusinessInsurance
Public liability, employers’ liability and the covers small businesses actually need, built around your trade, not a generic package.
Public liability, employers’ liability and the covers small businesses actually need, built around your trade, not a generic package.

 Employers’ liabilityStock & contentsCyber cover
 Compare from 20+ Trusted Insurers

Speak to a specialist 0330 808 1452
What is small business insurance?
Small business insurance isn’t a single policy, it’s the combination of covers a business builds around how it trades. Public liability and employers’ liability are the usual foundation, with stock, contents, professional indemnity or cyber added as needed.
Employers’ liability is the only cover most small businesses are legally required to hold, and only once they employ someone, everything else is driven by contracts, landlords and risk.
Small business insurance can include:
 Public liabilityEmployers’ liabilityProfessional indemnityBusiness interruptionCyber insuranceProduct liability

What insurance does a small business need?
Employers’ liability is the only cover most small businesses must hold by law. Everything else depends on what you do, where you work and what your contracts require.
You should seriously consider cover if you:
Employ anyone, even part-timeDeal face-to-face with the publicVisit customer or client premisesGive advice clients rely onAre asked for proof by a clientRent commercial premises
Is business insurance a legal requirement?
Only employers’ liability. It’s compulsory under the Employers’ Liability (Compulsory Insurance) Act 1969 from the moment you employ anyone, with fines of up to £2,500 a day for trading without it.
Other covers aren’t required by law, but you’ll usually be asked to prove you have them when you:
You’ll usually be asked to prove cover when you:
Sign a commercial leaseTake on a client contractJoin a trade body or associationWork on a construction siteAttend a trade show or market
How much employers’ liability cover does a small business need?
How much employers’ liability cover does a small business need?
The law sets a minimum of £5 million of employers’ liability cover, though most insurers provide £10 million as standard. Public liability limits are set by your contracts instead.
The law sets a minimum of £5 million of employers’ liability cover, though most insurers provide £10 million as standard. Public liability limits are set by your contracts instead.
| Level of cover | Typical for | Watch out for |
|---|---|---|
£1 million | Very small businesses with low public exposure | May be too low for many client contracts |
£2 million | Most small businesses and trades | Often the level councils and venues ask for |
£5 million | The legal minimum for employers’ liability | Required by law once you employ anyone |
£10 million | Larger contracts and most employers’ liability policies | Commonly provided as standard by insurers |

Top Tip
Employers’ liability is required even for unpaid volunteers and casual helpers, the test is the working relationship, not whether someone is on your payroll.
What could go wrong for a small business?
What could go wrong for a small business?
Most small business claims come from an employee injury, a customer hurt on your premises, damage to stock or equipment, or a cyber incident involving customer data.
Most small business claims come from an employee injury, a customer hurt on your premises, damage to stock or equipment, or a cyber incident involving customer data.
Your employers’ liability policy covers the claim and the legal costs behind it.

Your insurance certificates explained
Once you’re covered we’ll send your documents, often the same day. If you employ anyone, your employers’ liability certificate must be displayed where staff can see it.
Failing to display it can bring a fine of up to £1,000, separate from the penalty for having no cover at all.
Your certificate typically shows:
Your business or trading nameYour insurer’s namePolicy numberPolicy start and renewal datesAny specific conditions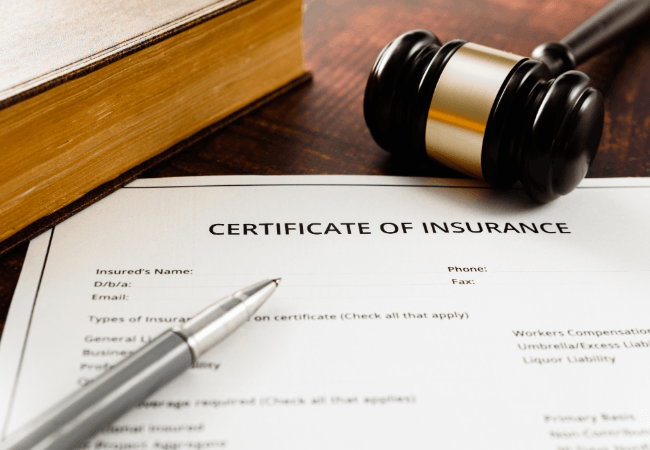
Cover often bought alongside small business insurance
Cover often bought alongside small business insurance
Most small businesses start with public and employers’ liability, then add cover for the things their business actually depends on, stock, equipment, data or income.
Most small businesses start with public and employers’ liability, then add cover for the things their business actually depends on, stock, equipment, data or income.
 Recommended
Employers’ Liability
Often a legal requirement once you employ staff, covering claims from employees injured at work.
 Recommended
Professional Indemnity
Covers claims that your advice, design or service was negligent and caused a client financial loss.
 Optional
Product Liability
Covers claims if a product you make, sell or supply causes injury or damage.
 Optional
Business Contents
Protects your equipment, stock, fixtures and fittings against fire, theft and damage.
 Optional
Business Interruption
Helps with lost income and ongoing costs if an insured event stops you trading.
 Popular
Commercial Combined
Bundle public liability with your other covers into one policy and one renewal date.
How much does small business insurance cost?
There’s no fixed price. Staff numbers, turnover and what you actually do drive most of it, a two-person consultancy and a ten-person workshop are priced very differently.

What your business does
Physical, on-site or public-facing work costs more to cover than desk-based work.
Claims history
A clean claims record helps keep premiums down at renewal.
Number of employees
More staff means more employers’ liability exposure, the one cover you must hold.

Level of excess
A higher voluntary excess usually lowers your premium.

Annual turnover
Higher turnover generally means higher limits and a higher premium.
Premises and stock values
What you hold and where you trade from affects your contents and stock cover.
How to get small business insurance
How to get small business insurance
Getting small business insurance takes four steps: tell us about your business, choose your covers, compare specialist insurers, then get your documents, often the same day.
Getting small business insurance takes four steps: tell us about your business, choose your covers, compare specialist insurers, then get your documents, often the same day.

Tell us about your business
What you do, your turnover and whether you employ anyone.

Choose your covers
Public liability, employers’ liability, stock and any extras.

We compare specialist insurers
We search our panel of 20+ UK insurers.

Get covered and get your documents
Receive your certificates, usually the same day.
 UK-based specialist advisersAccess to specialist insurersNo obligation, just expert help

Trusted by thousands of businesses across the UK
Trusted by thousands of businesses across the UK
From everyday business insurance to complex specialist cover, our customers trust Insurance Revolution to find the right protection and provide expert support when it matters.
From everyday business insurance to complex specialist cover, our customers trust Insurance Revolution to find the right protection and provide expert support when it matters.
Small business insurance FAQs
Small business insurance FAQs
Straight answers on what you need, what’s required and cost.
Straight answers on what you need, what’s required and cost.
There’s no single policy. Employers’ liability is legally required once you employ anyone; most small businesses add public liability, then stock, contents, professional indemnity or cyber depending on what they do.
Still have questions?
Our advisers are here to help you find the right solution.